The Ultimate Guide to Creating a Successful Employee Recognition Program for Financial Services
Financial services enters 2026 with a retention problem that is quieter than the 2022 peak but no less costly. Sector voluntary turnover runs around 13%, but that average hides sharp differences by role: executives churn near 5%, while 60% of retail bank tellers leave within a year and 15% within three months (Retensa, 2026; Pathstream, 2024). Non-officer bank turnover was still 19.8% in 2023, down from a 23.4% peak (Crowe), and Quantum Workplace data classifies 35% of banking employees as a retention risk — a modeled estimate (Visbanking, 2026). Replacing a skilled professional costs a methodology-dependent 50–150% of salary, and every departure puts client relationships at risk.
An employee recognition program is one of the most direct, lowest-cost levers on that problem — though it works best alongside, not instead of, competitive pay and clear career paths, which matter especially for the scarce AI, cyber, and regtech skills 84% of firms are raising pay to secure (Robert Half, 2026). For those roles in a genuine bidding war, recognition is a weak lever — pay and opportunity dominate; recognition does its strongest work across the broad workforce, not the hottest few skills. What recognition adds is reinforcement of the client-service and compliant behaviors your firm runs on.
This guide outlines 13 financial-services-specific steps to build a program that reduces turnover, strengthens client relationships, and reinforces a culture of doing right by clients.


Get Executive and Board Buy-In
Make the case in the terms a financial-services leadership team and board already track: return, risk, and cost. The numbers are concrete — with replacement costs at 50–150% of salary and 35% of employees flagged as retention risks, even a modest reduction in regretted attrition pays for the program many times over (Retensa; Visbanking, 2026). Frame it as risk management, too: turnover in compliance, risk, and relationship roles is an operational and regulatory exposure, not just an HR metric. A stronger employee value proposition is what keeps critical talent from moving to the competitor down the street.
Appoint a Program Manager With Cross-Functional Reach
Give the program a clear owner empowered to make it work across a firm that spans branches, advisory teams, lending or trading desks, and back-office operations. In financial services the critical requirement is reach across silos: recognition that lives only in the retail branch network, or only in the front office, recreates the very divides that hurt collaboration and client service. The owner should have the authority to operate firm-wide, not just in one business line.
Choose a Program Type That Fits a Regulated, Relationship-Driven Business
Align the program to the outcomes you need — lower frontline and specialist turnover, stronger client-service scores, better cross-functional collaboration. Two considerations set financial services apart. First, keep recognition distinct from the heavily-regulated incentive and sales compensation your firm already runs; recognition for great service or teamwork is straightforward, but anything touching sales performance is a compliance matter (see step 8). Second, design for a multi-segment workforce — retail, advisory, operations, technology, compliance — whose motivations differ.
It’s often said the employee ‘is the product’ in financial services; that’s truest for client-facing advisory and relationship roles and less so for back-office functions, so design for both rather than assuming one model fits all.
Define a Realistic Budget
A common benchmark is roughly 1% of payroll for recognition and rewards (WorldatWork, 2024) — calibrate it to your firm’s size and goals rather than treating it as a rule, and justify it by the outcome you’re buying. The return case is strong because replacement costs are high (50–150% of salary) and salary budgets have normalized to a disciplined 3–4%, applied selectively to critical roles (BalancedComp, 2026).
Recognition is a cost-effective complement to that targeted-pay strategy: it reaches the whole workforce and improves the retention that selective raises alone don’t solve. Set the budget against a specific target and measure against it (see step 13).

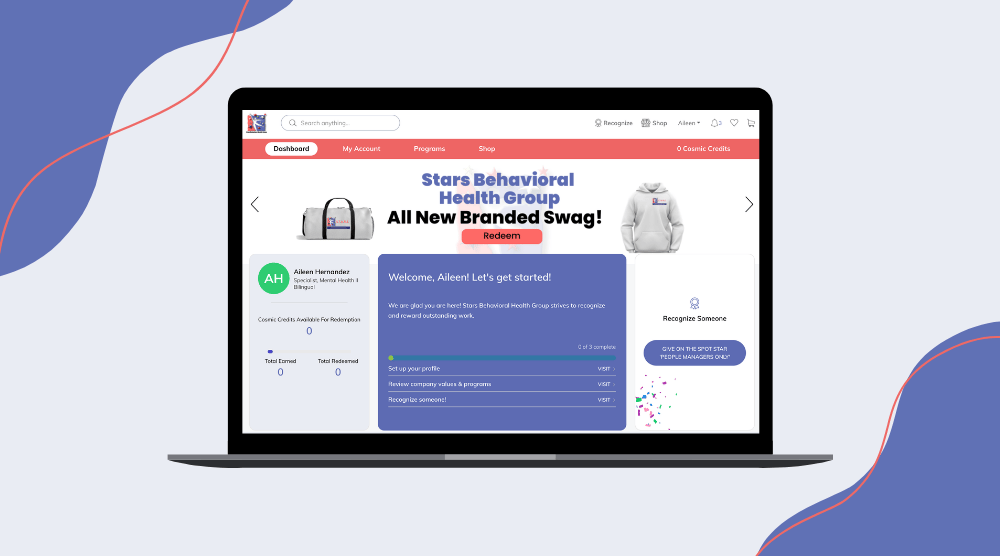
Implement the Right Recognition Software
The right platform makes recognition consistent across front-office, back-office, branch, and remote populations rather than dependent on individual managers. Look for flexible, cloud-based software that integrates with your systems and — for a regulated institution — meets the security, access-control, and audit expectations you’d apply to any enterprise tool.
It should reach every segment equally, standardize recognition firm-wide, and reduce the administrative load on HR.
Set Clear, Client- and Retention-Linked Goals
Define SMART goals — specific, measurable, achievable, relevant, time-bound. The highest-value goals connect recognition to metrics leadership already watches: reduce regretted attrition in critical roles, lift client-satisfaction or Net Promoter scores, improve first-year retention where frontline churn concentrates, or strengthen the cross-functional collaboration relationship banking depends on.
Communicate responsibilities clearly and give every team a target worth striving for.
Align Recognition With Your Values and Client-First Mission
Recognition lands hardest when it reinforces what your firm says it stands for — client trust, integrity, prudent risk-taking, and service. Recognizing the behaviors that build client confidence and uphold compliance signals, visibly, that the firm rewards doing right by the client and the rules. One caution: recognition has to feel genuine. Recognition that reads as transactional or box-ticking can ring hollow and even undercut the intrinsic motivation professionals bring to the work (Deci & Ryan, 2000) — so tie it to real contributions and client impact, not generic praise.
The same caution applies to teams whose roles automation is reshaping: recognition offered in place of honesty about their future will read as hollow, and no amount of praise substitutes for straight talk about where the work is going.
Establish Clear Recognition Policies and Procedures
Define what qualifies as recognition-worthy, who can recognize whom, and when and how it happens — clarity that matters more here because recognition sits near sensitive compensation and incentive structures. Keep recognition distinct from, and complementary to, formal incentive comp; anything that could be read as rewarding sales of specific products or hitting sales targets belongs with your compliance-governed comp plans, not your recognition program (a distinction that regulations such as Reg BI and UDAAP make consequential).
Make sure policies explicitly include the roles that keep the firm running but rarely face clients — compliance, risk, operations, and technology. And remember non-monetary recognition, a specific thank-you or acknowledgment of a well-handled client issue, often carries as much weight as points.

Offer Rewards That Fit a Financial-Services Workforce
Provide a relevant, appealing range of rewards from reputable vendors who deliver reliably. A financial-services workforce spans very different populations — from early-career analysts to seasoned relationship managers — so choice-based, flexible rewards outperform one-size-fits-all gifts. Let employees select what’s meaningful, and consider rewards that resonate with professionals who value growth: development, certifications, and experiences alongside everyday redemption options.
For high-competition specialist roles, meaningful recognition and development are a genuine retention tool — though not a substitute for market-competitive pay.
Create an Engaging, Social Recognition Experience
Increase adoption with gamification, social recognition, and team-collaboration features. Social recognition builds a transparent, visible culture of appreciation; team features let colleagues celebrate client wins together. In financial services, social recognition is a powerful bridge across the front-office / back-office / branch divides that otherwise leave teams siloed — helping compliance, operations, and technology feel as seen as the client-facing staff whose results are more visible. Use gamification thoughtfully, and keep it clearly separate from any regulated sales metric.
Promote Fairness Across Roles, Functions, and Locations
Ensure equal recognition opportunity so no one feels overlooked based on their function, location, or how client-facing their role is. This is a real risk in financial services: revenue-generating, front-office staff are naturally more visible than the compliance, risk, operations, and technology professionals who protect and enable the business — and under-recognizing those specialized, hard-to-replace roles is exactly where costly turnover starts. Watch, too, that the recognition program itself doesn’t simply mirror the existing pay-and-prestige tilt toward revenue producers.
Track recognition distribution across functions and locations so fairness becomes a managed outcome, not an assumption (see step 13).
Improve Internal Communication
A well-functioning program depends on clear internal communication across a firm that may span many locations and business lines. Partner with internal communications to deliver consistent messaging about the program’s goals through the channels employees actually use, and make wins visible across the organization.
When employees everywhere — not just at headquarters — see recognition happening and understand how to participate, participation and cross-firm connection both rise.
Measure and Improve the Program’s Impact
Measurement is what makes recognition a strategic program rather than a morale gesture — and financial-services leaders expect it. Track the metrics leadership owns: regretted attrition by role and function (frontline vs. specialist vs. officer), recognition participation and distribution (to catch the fairness gaps in step 11), engagement scores, and the link to client outcomes like satisfaction, retention, and relationship depth.
The connection between employee experience and client experience is well documented across service industries (Heskett et al., 1994; Gallup & Workhuman, 2023), though the direct evidence is largely cross-industry rather than banking-specific — so treat your own measured results as the real test. Measure during and after, diagnose root causes, and refine.

Strengthen Retention Across Your Financial Services Workforce
Your people shape every client interaction, from the branch to the back office. Build a recognition strategy that reinforces client-first behaviors, strengthens engagement, and helps retain the talent your organization depends on.